

Personal Income Tax for Foreign Experts in Vietnam: A Guide to Tax Finalization and Cost Optimization
Along with the explosion of FDI capital flows and the trend of deep integration, Vietnam is becoming an ideal destination for the global highly skilled knowledge workforce. The presence of international CEOs, Chief Engineers, and Consultants brings invaluable value to businesses. However, accompanying the human resource advantage is a massive challenge in terms of legal compliance, especially the problem of PIT for foreign experts.
Vietnam’s tax legal system regarding foreign labor is considered quite complex and constantly changing. Failure to grasp regulations on residency, taxable income, and the deadline for expat tax finalization can lead to massive administrative fines, and even exit bans for violating individuals. For the sponsoring enterprise, negligence in managing PIT for foreign experts not only damages reputation but also unreasonably increases operating costs.
This in-depth article is designed as a comprehensive legal handbook, providing Chief HR Officers (CHROs), Chief Accountants, and the expats themselves with the most thorough insight. We will detail how to determine residency status, guide the expat tax finalization process, and especially share completely legal tax cost optimization strategies, helping protect cash flow for both individuals and businesses subject to PIT for foreign experts.
Financial expert’s perspective: The most common mistake of FDI enterprises is rigidly applying the Vietnamese tax calculation method to foreigners. Correctly identifying a “Resident individual” or “Non-resident individual” is the key to determining all financial obligations. If miscalculated, the payable amount of PIT for foreign experts can differ by tens to hundreds of millions of VND each year, bankrupting all initial tax cost optimization plans. Furthermore, incorrect expat tax finalization procedures can freeze cash flows.
Determining residency status: The milestone defining tax obligations
In Vietnam’s tax law, nationality is not the determining factor, but “Residency status” is the lens through which the Tax authority examines. Every strategy for expat tax finalization and optimizing PIT for foreign experts must begin with correctly identifying which group the individual belongs to.
According to Circular 111/2013/TT-BTC, a foreign expert is considered a Resident individual when meeting one of the two basic conditions below:
- Being present in Vietnam for 183 days or more in a calendar year or in 12 consecutive months from the first day of arrival in Vietnam.
- Having a regular place of residence in Vietnam, including having a registered permanent residence or a rented house to live in Vietnam under a lease contract of 183 days or more in the tax year.
Conversely, if they do not meet the above conditions, they will be classified as a Non-resident individual. This classification leads to two completely different methods of calculating PIT for foreign experts:
| Comparison Criteria | Resident individual | Non-Resident individual |
|---|---|---|
| Scope of taxation | Subject to tax on income arising both inside and outside the territory of Vietnam (Global income), regardless of where the income is paid. | Only subject to tax on income arising in Vietnam (Vietnam-sourced income). |
| Applied tax tariff | Apply the partially progressive tax tariff (from 5% to 35%), similar to Vietnamese citizens. This directly affects PIT for foreign experts. | Apply a fixed flat tax rate of 20% on total income arising in Vietnam. |
| Family deductions | Allowed to apply family deductions (self, dependents) to optimize PIT for foreign experts. | Absolutely not allowed to apply any family deductions. |
| Finalization obligations | Mandatory to perform expat tax finalization at year-end. | No need to perform expat tax finalization procedures (tax withheld at source). |
Accurately tracking the number of days present in Vietnam (via immigration stamps on the Passport) is extremely important. Support from the legal HR expert team of N.N SERVICE will help businesses establish early warning systems, avoiding the wrong application of tax rates leading to arrears risks.
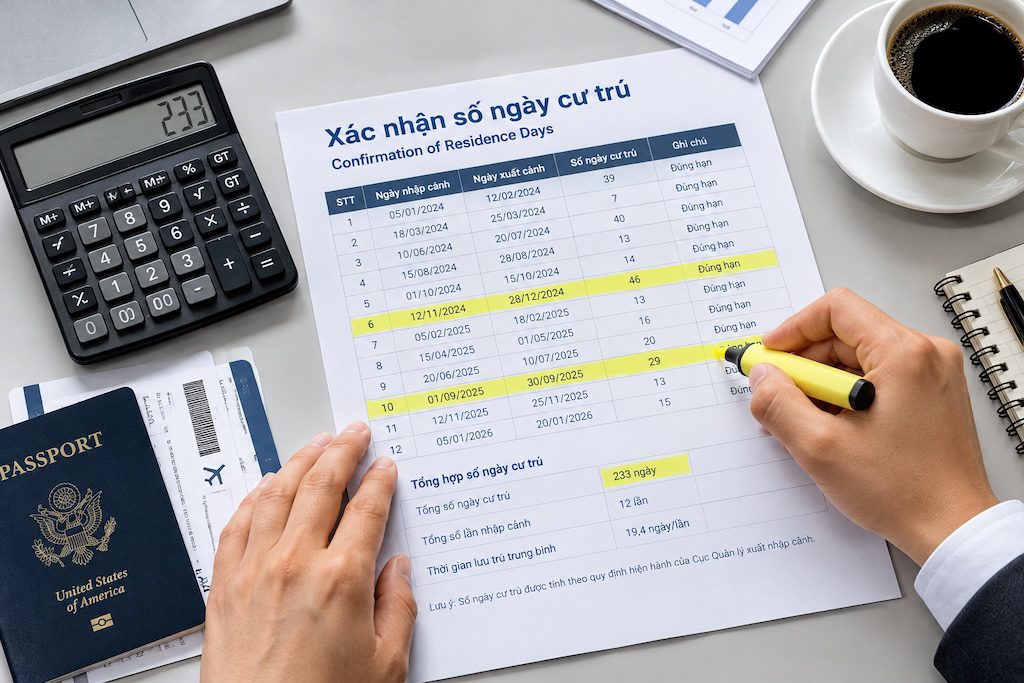
Accurately determining “Resident” or “Non-resident” status is the first step to avoid legal risks before expat tax finalization.
expat tax finalization process: Milestones to remember
For experts determined as “Resident individuals”, performing expat tax finalization is a mandatory obligation, even if the enterprise has deducted their tax monthly. This process requires close coordination between the FDI enterprise’s accounting department and the employee themselves.
Take special note, 2026 continues to strictly apply the digitization of administrative procedures. Most procedures for expat tax finalization must be done via the electronic Tax system (eTax). Below are the core timelines and dossiers:
1. Year-end financial finalization (For those continuing to work)
If the expert continues to work in Vietnam into the next year, the deadline to submit the expat tax finalization dossier is at the latest the last day of the 4th month from the end of the calendar year (usually April 30). However, if the individual authorizes the income paying organization (the company) to finalize on their behalf, the deadline will be the last day of the 3rd month (usually March 31).
2. Finalization upon contract termination and returning home
This is the situation most prone to errors. Before foreign experts end their employment contract and exit back home, they MUST complete the expat tax finalization procedure with the Tax authority, at the latest by the 45th day from the exit date. The immigration agency has the right to suspend the exit if it discovers the individual still owes tax.
| Legal document type | Purpose of use in the finalization dossier |
|---|---|
| Tax Finalization Declaration (Form 02/QTT-TNCN) | Official form to declare total global income and payable tax for expat tax finalization. |
| Letter of Global Income Confirmation | Confirm income arising abroad (paid by the parent company) to correctly calculate PIT for foreign experts according to the global income principle. |
| Copy of Passport | Cross-check immigration timelines to prove resident individual status for expat tax finalization. |
| Tax Deduction Receipt | Prove the amount of tax paid in Vietnam and abroad (to apply the Agreement on avoidance of double taxation). |
| Dossier proving dependents | Birth certificate, marriage registration (consular legalized) to optimally reduce tax costs. |
Collecting documents from abroad (like the Letter of Income Confirmation) usually takes a lot of time. Proactiveness from the Tax consulting experts of N.N SERVICE will help businesses plan dossier preparation early, ensuring a smooth expat tax finalization process.
Legal tax cost optimization strategies for experts
With progressive tax rates up to 35%, PIT for foreign experts creates a massive financial burden. However, the legal system still allows businesses to flexibly utilize the Salary Package structure to optimize PIT for foreign experts in a completely legal way, without violating the law.
The core principle of minimizing PIT for foreign experts is converting a portion of cash income (highly taxed) into in-kind benefits or tax-exempt allowances. Below are 3 spearhead strategies:
Strategy 1: Housing cost optimization (Housing Allowance)
Under current regulations, the house rent, electricity, water, and accompanied services that the employer pays on behalf of the foreign expert will be included in taxable income. However, the maximum calculated level does not exceed 15% of total taxable income arising in Vietnam (excluding house rent).
Tax optimization application: Businesses should not give cash allowances for experts to rent houses themselves (as it will be taxed at 100%). Instead, the business should sign the lease contract for a high-end apartment or villa directly with the landlord through the support of the N.N REALTY professional brokerage system. This structure helps cap the expert’s taxable income for housing at 15%, generating huge savings on PIT for foreign experts.
Strategy 2: Specific tax-exempt allowances
To minimize PIT for foreign experts, the Labor Contract and the Financial Regulations of the enterprise need to clearly stipulate the following welfare expenses (fully tax-exempt if there are full valid invoices and documents):
- Round-trip airfare costs: Once a year for the expert to take leave to visit their home country (excluding airfare for wife/children).
- Tuition fees for the expert’s children: Tax-exempt for the tuition portion from preschool to high school at schools in Vietnam (paid directly to the educational institution).
- Relocation allowance: A one-time relocation subsidy for foreigners coming to reside in Vietnam, an effective tool before expat tax finalization.
Strategy 3: Utilizing the Double Taxation Avoidance Agreement (DTA)
Vietnam has signed Double Taxation Avoidance Agreements with over 80 countries. If the foreign expert is a tax resident of a country that has signed a DTA with Vietnam, they may be tax-exempt in Vietnam for certain income (e.g., income from technical services, royalties) if meeting the presence time conditions.
This is the most powerful tool to reduce PIT for foreign experts, but the dossier procedure (especially the Tax Residence Certificate issued by foreign authorities) is extremely complex, requiring the intervention of seasoned legal consultants during expat tax finalization.
Restructuring allowances and welfare is the most legal method to optimize the cost of PIT for foreign experts.
Inspection Risks: The Global Income “Trap” and Benefits in kind
Besides optimizing PIT for foreign experts, managing inspection risks is a vital task. Tax authorities currently apply Cross-checking measures on international data via multilateral agreements. Naivety in handling expat taxes will pay a heavy price.
The biggest risk lies in the “Global income trap”. Many FDI enterprises apply a Split payroll model: A portion of salary is paid in Vietnam for expat tax finalization, while the majority is paid by the parent company abroad and deliberately concealed. This behavior is very easily detected nowadays. If inspected, the business will face tax arrears, late payment penalties (0.03%/day), and administrative violation fines, seriously affecting the legal conditions of the entire project.
The second risk is providing “Benefits in kind” like private shuttle cars, Golf memberships, and international life insurance. If these items explicitly bear the expert’s name, they must be added to the taxable income for PIT for foreign experts. Businesses should consult N.N SERVICE’s accounting experts to restructure these welfare packages into general company expenses to dodge legal risks during expat tax finalization.
Lease contracts under the business’s name help cap the taxable income portion of rent at 15% for PIT for foreign experts.
Frequently Asked Questions (FAQ)
Below are the 6 most practical questions related to PIT for foreign experts and how to optimize taxes that HR Directors frequently ask when working with the N.N GROUP ecosystem in HCMC:
1. If a foreign expert signs a 2-month probation contract, how is tax calculated?
For contracts under 3 months or probation, income will be deducted 10% at source (if having a Tax Code) or 20% (if residency status is undetermined) on the total income paid each time from 2,000,000 VND upwards. The tax optimization here is to ensure they register a Personal Tax Code promptly before expat tax finalization.
2. If the company pays university tuition for the foreign expert’s child, is it tax-exempt?
No. According to regulations on PIT for foreign experts, the tax-exempt tuition amount only applies from preschool to high school. University tuition will be included in the expert’s taxable income during expat tax finalization.
3. Can a resident foreign expert claim family deductions for parents abroad?
Yes, but the procedure is very complex. To optimize PIT for foreign experts through this, the expert must provide full dossiers proving the relationship, proving parents are beyond working age and have no income. All documents from abroad must be translated, notarized, and consular legalized for expat tax finalization.
4. How does the company handle incurred tax when an expert returns home mid-term?
Before the expert exits, the company must urgently perform expat tax finalization with the Tax authority. If there’s surplus tax, process a refund; if deficient, pay additionally. The company is responsible for withholding the final salary to ensure funds to pay the tax.
5. Is the round-trip airfare for the expert’s family leave tax-exempt?
No. The 1 time/year tax-exempt round-trip airfare cost solely applies to the foreign employee (expert) themselves. All airfare costs paid on behalf of the wife, children, or relatives must be added to taxable income.
6. What is the best solution to avoid risks when declaring global income?
The safest and most transparent solution is requesting the parent company to provide a Letter of Income Confirmation or Payslip abroad, then authorizing a professional unit like N.N SERVICE to synthesize and perform expat tax finalization according strictly to the standards of the Vietnamese Tax authority for PIT for foreign experts.
Conclusion: Confident compliance, protecting talent with N.N GROUP
Understanding and excellently managing PIT for foreign experts is not only a legal compliance obligation but also an art of corporate financial management. Acumen in utilizing legal tax optimization policies for PIT for foreign experts is the key for businesses to design attractive remuneration packages, retain international talent, and concurrently protect cash flow safety and brand reputation.
However, the complexity of the tax law system and the international nature of the income source always harbor unpredictable risks for expat tax finalization. To turn administrative challenges into competitive advantages, multinational corporations need the companionship of a professional “All-in-One” B2B consulting ecosystem like N.N GROUP:
- Through N.N SERVICE, our team of accounting experts and senior lawyers will act as an “external department”, assisting businesses in reviewing salary structures, applying for Tax Codes, registering dependents, and representing you to perform the entire expat tax finalization process accurately, completely eliminating the risk of disallowed inspections.
- Synchronizing with N.N REALTY, we deliver perfect solutions for PIT for foreign experts by representing businesses to find and negotiate lease contracts for high-end apartments and villas for experts. Ensuring the housing cost structure always remains within the safe 15% limit, bringing a wonderful residential experience for experts in the Vietnamese market.
Don’t let administrative procedure errors damage the interests of core experts and cause legal risks for the company. Let the N.N GROUP ecosystem become your strategic partner, protecting finances and creating the safest compliance roadmap for your business’s expat tax finalization today!