

Home Loans in 2026–2027: How Much Will You Have to Pay Each Month After Promotional Interest Rates Expire?
The real estate credit picture in Vietnam during the 2026-2027 period is revealing starkly contrasting colors. On one hand, commercial banks continuously launch home loan packages with extremely attractive fixed interest rates in the first 12 to 24 months, fluctuating from 5.5% to 6.5%/year to stimulate the market.
On the other hand, tens of thousands of borrowers are facing a financial shock (Payment Shock) when passing the credit “honeymoon” phase. The most haunting question for both individual investors and speculators right now is: After promotional interest rate, how much must be paid each month, and how to prevent cash flow from breaking under the pressure of floating interest rates?
The nature of real estate credit packages is the transfer of risk from the bank to the borrower. Most current home loan contracts are designed according to the principle: Floating interest rate = Base rate (or 12-24 month term deposit rate) + Fixed margin (usually from 3.5% to 4.5%).
When the macroeconomic economy fluctuates, rising inflation forces the State Bank to tighten monetary policy, and deposit interest rates will bounce strongly.
At this time, the borrower will have to bear all the inflated capital costs. Failing to accurately project the after promotional interest rate scenario will push the Debt-to-Income (DTI) ratio beyond the safe threshold, leading to the risk of bad debt and property foreclosure by the bank.
This in-depth financial analysis will provide an empirical lens, dissecting the calculation formulas of commercial banks.
We will simulate in detail cash flow scenarios to answer exactly how much must be paid each month, while outlining legal and financial strategies to help borrowers restructure their debts, protecting their assets from liquidation risks in the context of credit tightening.
Credit analyst’s perspective: The fatal mistake of 80% of home loan borrowers is only looking at the amount payable in the first year to make a purchasing decision.
In the 2026-2027 period, targeted inflation and expected exchange rates will have unpredictable adjustments. After promotional interest rate, the monthly payable amount can skyrocket by 30% to 50% compared to the beginning.
Investors must prepare a Liquidity Buffer equivalent to at least 6 months of principal and interest at the highest floating interest rate (Stress Test) to survive the tightening cycle.
The financial trap nature of floating interest rates (Floating Rate)
To control cash flow, borrowers need to understand the mechanism of interest rate formation after the grace period. When the fixed interest rate period ends, the home loan contract will automatically switch to a floating interest rate mechanism. This mechanism is designed by banks to protect their Net Interest Margin (NIM) against capital market fluctuations.
The general formula applied across the Vietnamese commercial banking system is: Floating interest rate = Base Rate + Margin.
Where the Margin is a constant rigidly fixed in the credit contract right from the signing, usually ranging from 3.0% to 4.5% depending on each bank’s risk appetite and the customer’s credit history (CIC).
However, the “fatal variable” lies in the Base Rate. Each bank has a different way of defining the Base Rate. The state-owned bank group (Big 4) often uses the 12 or 24-month deposit interest rate as an anchor.
Conversely, many private commercial joint-stock banks apply an internal “Reference rate” concept, which is inherently ambiguous and unilaterally issued by the bank periodically every month/quarter.
This very ambiguity puts the borrower in a passive position. After promotional interest rate, the borrower is almost unable to intervene in the bank’s adjustment of the Base Rate.
If the market deposit interest rate rises to 7%/year, plus a 4% margin, the actual home loan interest rate will soar to 11%/year. This leap shatters the entire initial financial plan, placing immense pressure on the question of how much must be paid each month.
The Psychological Toll of Financial Uncertainty
Beyond the strict financial metrics and amortization tables, the transition to floating interest rates exacts a severe psychological toll on borrowers. The constant anxiety of unpredictable monthly payments can strain family dynamics and severely distract business owners from their core operations.
A home loan that was initially perceived as a pathway to wealth accumulation quickly morphs into a source of chronic stress when the macroeconomic environment tightens. This psychological burden often leads to suboptimal decision-making, such as panic-selling assets at a loss or taking on toxic short-term debt to bridge temporary cash flow gaps. A robust financial strategy must therefore incorporate not just mathematical buffers, but also psychological preparedness, ensuring that investors remain objective and resilient when faced with rate hikes.
Anatomy of a real-world problem: The principal and interest cash flow shock
To quantify the risk, we will perform a Stress Test on a popular home loan in the market today.
Assume a customer buys an apartment in HCMC, needs a bank loan of 2,000,000,000 VND (Two billion VND), a loan term of 20 years (240 months), the repayment method is declining balance (principal divided equally monthly, interest calculated on the actual outstanding balance).
The bank offers a promotional package: Fixed interest rate of 6.0%/year for the first 12 months. From the 13th month, the floating interest rate is expected at 11.0%/year. The table below will dissect the cash flow in detail to answer exactly: after promotional interest rate, how much must be paid each month:
| Payment Period | Monthly Principal (VND) | Interest Payable (VND) | Total: How much to pay each month? |
|---|---|---|---|
| 1st Month (During 6.0% promotion) | 8,333,333 | 10,000,000 | 18,333,333 VND |
| 12th Month (End of 6.0% promotion) | 8,333,333 | 9,541,667 | 17,875,000 VND |
| 13th Month (After promotional interest rate, jumps to 11.0%) | 8,333,333 | 17,416,667 | 25,750,000 VND (Increases ~44%) |
| 24th Month (Floating rate 11.0%) | 8,333,333 | 16,576,389 | 24,909,722 VND |
Looking at the actual data, the harshness of the credit contract is clearly revealed. Transitioning from the 12th to the 13th month, the interest amount payable nearly doubles (from 9.5 million to 17.4 million), pushing the total financial burden from 17.8 million to 25.7 million VND.
A sudden 44% increase in monthly costs will immediately strangle the living cash flow of households or cause negative rental cash flow for B2B investors.
Failing to measure how much must be paid each month when entering the floating rate cycle is the core reason why a series of real estate properties are foreclosed by banks, becoming bad debts.
Before deciding to use financial leverage, investors should request the brokerage expert team of N.N REALTY to establish an Amortization Schedule for the worst-case scenario to determine if the net income is strong enough to carry the asset.
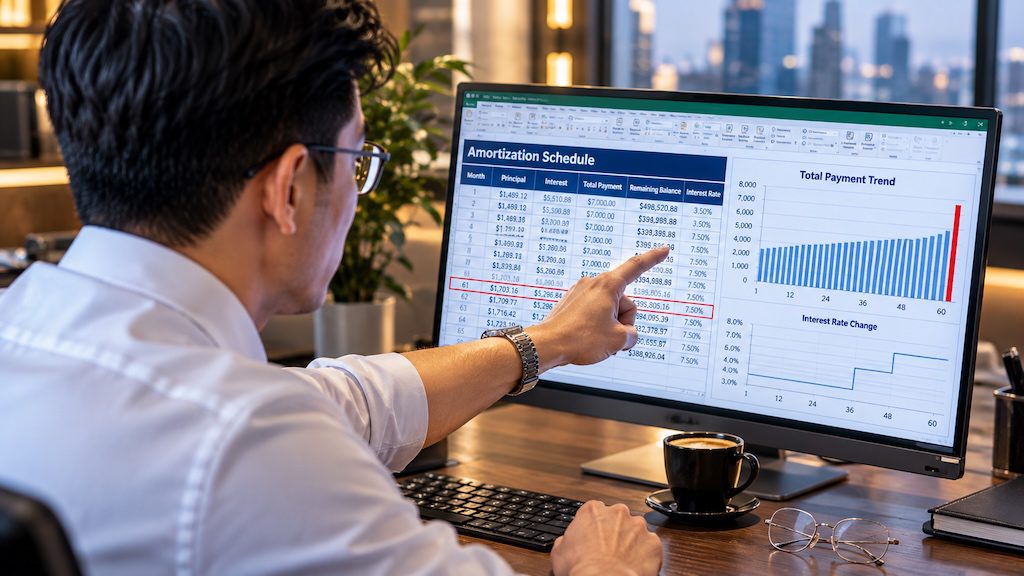
Accurately calculating the declining balance is a vital step to ensure cash flow is not disrupted when interest rates switch to a floating state.
The Impact of Global Monetary Policy
To truly anticipate the trajectory of domestic interest rates, one must look beyond Vietnam’s borders. The State Bank of Vietnam’s monetary policy is inextricably linked to global macroeconomic shifts, particularly the decisions made by the US Federal Reserve. When global central banks embark on a quantitative tightening cycle to combat inflation, emerging markets like Vietnam are forced to raise their domestic rates to prevent severe currency depreciation and capital flight. Therefore, borrowers analyzing their home loan obligations must incorporate global economic indicators into their stress tests. Anticipating these global macroeconomic ripples allows savvy investors to lock in long-term fixed rates before the domestic market reacts, effectively shielding their portfolios from imported inflation and the subsequent spikes in borrowing costs.
Legal decoding: Debt group transition and asset liquidation risks
When the pressure to repay a home loan exceeds the cash flow’s endurance, legal risks will arrive extremely quickly. The National Credit Information Centre (CIC)’s debt classification system has no room for leniency.
After promotional interest rate, as soon as the borrower does not prepare enough money to pay the exact amount required each month according to the bank’s notice, the debt group jumping process will begin.
Delayed payment from 10 to 90 days, the loan will be transferred to Attention-needed Debt (Group 2). Exceeding 90 days, it officially becomes Bad Debt (Group 3).
The consequence of falling into Group 3 is a disaster for any financial profile: The borrower will be blocked from all credit access efforts across the entire banking system for the next 5 years.
Simultaneously, the bank will apply an overdue penalty interest rate, usually 150% of the currently applied interest rate, causing the outstanding balance to swell exponentially.
The next step, the bank will activate the collateral seizure clause according to the mortgage contract. The process of foreclosing (liquidating) assets is usually carried out via auction or filing a lawsuit in court.
In this scenario, the real estate value is often appraised much lower than the market price, causing the home loan borrower not only to lose the asset but also to risk carrying the remaining unpaid principal debt.
Debt refinancing strategy and financial restructuring according to Circular 06
Instead of sitting and waiting for the interest rate bomb to explode after promotional interest rate, savvy investors always have a plan to proactively restructure their cash flow. Since September 2023, the State Bank has issued Circular 06/2023/TT-NHNN, opening a lifeline for home loan borrowers: Allowing customers to borrow capital at one bank to prematurely repay debt at another bank.
This is an extremely powerful Interest Arbitrage tool. Suppose you are carrying a loan with a floating interest rate of 11.5%/year at Bank A.
Instead of submitting, you can search for Bank B which has a new promotional loan package of 6.0%/year fixed for 24 months. “Transferring the debt” to Bank B will help you reshape the problem of how much to pay each month, cutting tens of millions of VND in interest every month.
However, this Refinancing strategy is not simple at all. Bank B will perform Re-underwriting from the beginning, including:
- Asset Appraisal: The real estate value at present may be appraised lower than when purchased, leading to the new loan limit not being enough to settle the old debt.
- Re-proving income: You must provide all salary statements and house lease contracts to prove your repayment capacity at the present time.
- Prepayment Penalty: Bank A will collect a penalty fee (usually 1% to 3% on the remaining principal balance) when you settle early. You must do the math to see if the interest saved from Bank B can cover Bank A’s penalty fee and the new notary, mortgage release, and secured transaction registration fees.
To execute this complex strategy smoothly and without legal risks, entrusting it to the financial and legal expert team of N.N SERVICE is the optimal solution. They will directly appraise the loan plan, negotiate the financing ratio with the new bank, and handle the entire 3-party mortgage release-mortgage process in the safest way.
Applying Circular 06 to refinance debt between banks is a powerful interest arbitrage strategy helping customers relieve financial pressure.
Cash flow risk management from Commercial Real Estate
For B2B investors buying commercial real estate (Shophouses, offices, serviced apartments) using financial leverage, home loan pressure takes a different form.
The bank debt repayment cash flow depends directly on the Rental Yield. If bank interest rates rise higher than the rental profit margin, the investor will fall into a “Negative Cash Flow” state.
To protect profit margins, investors need to establish lease contracts with Escalation clauses linked to the Consumer Price Index (CPI). However, increasing rent too sharply can cause tenants to leave, leaving the premises vacant (Vacancy rate increases), leading to a complete loss of cash flow for many months. This is a fatal bottleneck when the fixed term ends.
The best defense solution is to optimize asset functionality and seek highly stable Corporate tenants. The intervention of professional brokerage and property management units can help increase the commercial exploitation value of real estate.
Secondary investors can consult the spatial architecture renovation handbook from N.N REALTY to upgrade premises, thereby reasonably raising rents, creating surplus revenue to offset debt repayment pressure when the question of how much to pay each month becomes heavy.
Increasing Rental Yield is the most perfect layer of defense for B2B investors to survive the credit tightening cycle.
Frequently Asked Questions (FAQ) about home loan credit
Below are the 6 most highly practical issues that the investor and homebuyer community frequently raise when facing the risk of being after promotional interest rate and the problem of how much must be paid each month:
1. How is the Prepayment Penalty usually calculated?
2. How often is the Base Rate used to calculate floating interest updated?
3. Is the bank allowed to arbitrarily increase the Margin when inflation is high?
4. Should short-term capital sources (consumer loans, credit cards) be used to pay the principal debt when the promotional interest rate ends?
5. How do I know if the bank is calculating the monthly floating interest amount correctly?
6. If I am in Debt Group 2 (Attention-needed Debt), can I transfer the loan to another bank under Circular 06?
Conclusion
Using financial leverage for a home loan is an art of cash flow management, where the boundary between optimizing profit margins and falling into a debt disaster is extremely fragile. When the fixed term ends, the volatility of the financial market will expose the true capacity of the borrower.
Failing to project the scenario of how much must be paid each month is the biggest loophole leading to the risk of asset liquidation. However, if grasping the credit contract structure and proactively applying legal corridors like Circular 06, investors can completely restructure debt, master capital flow, and preserve their asset blocks in the long term.
For institutional and individual investors, planning a financial strategy cannot just rely on surface-level estimated numbers. To establish a solid defense shield against interest rate shocks and optimize commercial real estate exploitation efficiency, the N.N GROUP ecosystem provides a specialized and comprehensive solution suite:
- Through in-depth data from N.N REALTY, we support the Appraisal of collateral assets, search for business premises generating true positive cash flow, and provide architectural upgrade solutions to maximize rental yield.
- Accompanying N.N SERVICE, the financial and legal expert team will directly appraise debt refinancing plans, represent credit contract negotiations with financial institutions, ensuring your capital structure is always at the safest and most efficient level.
Don’t let floating interest rate pressure swallow your real estate investment fruits. Let the N.N GROUP ecosystem become a strategic partner, helping you restructure cash flow and master all financial risks today! Please refer to the document named “CODE WEB” for integrating digital solutions in these property management efforts.
Connect with Financial Consulting and Real Estate Management